Buying a home
Your path to buying a home
Buying is easier with a clear order of steps. Start with what you can comfortably afford, line up any grants, get pre-approved, then find the right home. We can help with both the home search and the loan.
Your roadmap to buying a home
From 'should I buy?' to the keys. Most purchases take 30 to 45 days from accepted offer to closing; the search before that is up to you.
Decide if buying is right for you
A week or twoCan I buy a house? →You
- Think about how long you plan to stay (buying usually pays off after 3 to 5 years)
- Compare the true cost of owning with your rent
We
- Talk it through with you, with no pressure and no obligation
Why it matters: Buying costs money up front (down payment, closing costs, moving) and you build equity over time. If you may move again within a couple of years, renting can work out cheaper.
Questions to ask
- How long will I stay in the area?
- Is my job and income steady?
- Do I have savings left over after the down payment for repairs and emergencies?
- What will I pay each month, including taxes, insurance and HOA fees, not just the loan?
- Who's involved
- You, and us if you'd like a second opinion. No cost.
- What it costs
- Free.
Tip: Try the Rent vs buy calculator with your real rent. It shows the year buying starts to come out ahead.
Know your budget
An eveningHow much can I afford? →You
- Work out a monthly payment you're comfortable with
- Check your credit and savings
We
- Show the true monthly cost, including taxes, insurance, HOA and CDD fees
Why it matters: The most a lender will approve isn't always the most you should spend. Your budget should leave room for savings, repairs and life.
Questions to ask
- What's my credit score, and is anything on my report wrong?
- How much do I have for the down payment and closing costs?
- What monthly payment would still let me save each month?
- Who's involved
- You. A free credit report is available at AnnualCreditReport.com.
- What it costs
- Free.
Tip: In Florida, insurance and HOA or CDD fees can add hundreds a month. Always budget for the full payment.
Get pre-approved
1 to 3 daysStart my pre-approval →You
- Apply online and send pay stubs, W-2s or tax returns, bank statements and ID
We
- Review your credit and income, compare loans from over 300 lenders, and give you a pre-approval letter
Why it matters: A pre-approval tells you exactly what you can borrow and shows sellers you're serious. Many sellers won't look at an offer without one.
Questions to ask
- Which loan types fit me (conventional, FHA, VA, USDA)?
- What would my rate and monthly payment be?
- How much cash will I need at closing?
- How long does the pre-approval last?
- Who's involved
- A licensed loan officer (that's us).
- What it costs
- Free. A credit check is part of it.
Tip: Shopping lenders within about 14 days counts as one credit inquiry in most scoring models.
Check for down payment help
About a weekFind down payment help →You
- Find out which grants and programs you may qualify for
We
- Match the program to the right loan and check its rules and deadlines
Why it matters: Florida has state and county programs that can help with the down payment and closing costs. Some are forgiven over time; others are repaid when you sell.
Questions to ask
- Do I qualify as a first-time buyer? (Often: no ownership in the last 3 years.)
- Is there an income or price limit?
- Does the help have to be repaid, and when?
- Is a homebuyer class required?
- Who's involved
- Your loan officer, and sometimes a housing counselor.
- What it costs
- Usually free. Some programs require a short class, often low cost.
Tip: Funds can run out. Ask early so it doesn't hold up your closing.
Choose your Realtor and see a few homes
1 dayGet matching homes sent to me →You
- Sign a written buyer agreement (needed before touring homes)
- List your must-haves and the areas you'd like to see
We
- Explain how we're paid, then set up an MLS search so new homes reach you first
What Bill does differently: Something Bill does early on: he takes you to see a few homes in your price range, so you see what your budget really buys before you commit to anything.
Why it matters: Your Realtor represents you: finding homes, checking value, writing the contract and negotiating. Since 2024, a written agreement is needed before any home tour, and it states how your agent is paid.
Questions to ask
- How are you paid, and can the seller contribute?
- How will you keep me updated?
- Can the agreement be short or limited to certain homes?
- Who's involved
- A licensed Realtor.
- What it costs
- Set out in your written agreement. Often paid wholly or partly by the seller, but it's negotiable.
Tour homes and choose one
Often 2 to 8 weeksHome viewing checklist →You
- Visit homes, compare neighborhoods, HOA rules and fees
We
- Show homes, pull recent sales, and run the real monthly cost for each one
Why it matters: Seeing several homes helps you know a good one when you find it. Notes and photos help you compare later.
Questions to ask
- How old are the roof, AC and water heater?
- What are the HOA or CDD fees, and what do they cover?
- Is it in a flood zone? What would insurance cost?
- What have similar homes nearby sold for?
- Who's involved
- You and your Realtor.
- What it costs
- Free.
Tip: Visit at different times of day: traffic, noise and light can change a lot.
Make an offer
1 to 3 daysEstimate my cash to close →You
- Agree the price, terms and closing date
- Pay the escrow deposit, usually within 3 days of acceptance
We
- Prepare the contract on the standard Florida forms and negotiate for you
Why it matters: Your offer is more than price: the deposit, inspection period, financing terms, closing date and any seller credit all matter.
Questions to ask
- What have similar homes sold for, and how long were they on the market?
- Should I ask for closing costs instead of a lower price?
- What happens to my deposit if the loan or inspection falls through?
- Who's involved
- You, your Realtor, the seller and their agent. The deposit is held by a title company or broker.
- What it costs
- An escrow deposit, often 1% to 3% of the price. It counts toward your purchase.
Tip: Never wire money based on an email alone. Call the title company on a number you know is real.
Inspections and insurance
Usually 10 to 15 daysWhat an inspector checks →You
- Have the home inspected (and a wind-mitigation and 4-point report)
- Get insurance quotes
We
- Review the reports with you and negotiate repairs or credits
Why it matters: The inspection period is your chance to find problems and walk away or renegotiate. In Florida, insurers often require a 4-point report on older homes, and a wind-mitigation report can lower your premium.
Questions to ask
- What are the biggest repairs, and roughly what would they cost?
- Will the roof and AC pass the insurer's checks?
- Is a termite (WDO) inspection or a survey worth getting?
- Who's involved
- Home inspector, insurance agent, sometimes a surveyor or termite inspector.
- What it costs
- Typical ranges: home inspection $350 to $600, wind-mitigation $75 to $150, 4-point $100 to $200, survey $350 to $600. Prices vary.
Tip: Get insurance quotes in the first few days. In Florida, insurance can change whether a home is affordable.
Appraisal and loan approval
2 to 3 weeksWhat underwriting means →You
- Answer document requests quickly
- Don't change jobs or open new credit
We
- Order the appraisal and steer the loan through underwriting to 'clear to close'
Why it matters: The lender checks the home's value (appraisal) and your paperwork (underwriting). 'Clear to close' means the loan is fully approved.
Questions to ask
- What happens if the appraisal comes in low?
- Is anything still outstanding on my file?
- When will I get my Closing Disclosure?
- Who's involved
- Your loan officer, the appraiser and the underwriter.
- What it costs
- Appraisal often $500 to $800, usually paid up front or at closing.
Tip: Big deposits, new credit cards, a car loan or a job change can delay or stop the loan. Ask us first.
Final check
3 days before closingWhat the Closing Disclosure is →You
- Review your Closing Disclosure
- Do the final walk-through
- Set up utilities in your name from closing day
We
- Check every figure on the Closing Disclosure and coordinate with the title company
Why it matters: By law you get the Closing Disclosure at least 3 business days before closing, so you can check the final numbers.
Questions to ask
- Do these numbers match my Loan Estimate?
- Were the agreed repairs done?
- Exactly how much do I bring, and how do I send it safely?
- Who's involved
- You, your loan officer, your Realtor and the title company.
- What it costs
- No extra cost.
Tip: Confirm wiring instructions by phone with the title company before sending any money.
Closing day: get your keys
About an hourWhat to do after closing →You
- Sign the documents and get your keys
- Apply for the homestead exemption by March 1
We
- Attend closing with you and stay on hand after you move in
Why it matters: You sign the loan and the deed is recorded. Then the home is yours.
Questions to ask
- Where are my copies of everything?
- Who do I pay, and when is my first payment?
- How do I get the garage remotes, codes and mailbox key?
- Who's involved
- Title company or closing attorney, you, and often your Realtor and loan officer.
- What it costs
- Your cash to close, from your Closing Disclosure.
Tip: See the After closing roadmap for your first-month checklist, including homestead.
Times are typical, not guaranteed; every purchase and sale is different.
Renting now?
Your rent is probably paying your landlord's mortgage. See what they likely pay, and how soon buying could come out ahead.
Rent vs BuyMoving to Florida, or buying from abroad?
Central Florida draws buyers from across the US and overseas. A few things that surprise newcomers:
Living in Florida: taxes, weather, schools and things to do →
- Home insurance is often higher than in other states, so get quotes early and include them in your budget.
- HOA and CDD fees: many newer communities have both. A CDD (Community Development District) charge appears on the property tax bill.
- Homestead exemption: once you own and live in the home as your main residence, apply to your county by March 1 to reduce your property taxes.
- Flood zones: check the flood zone and ask about flood insurance before you buy.
- Buying from abroad? Financing options exist for some overseas buyers, and Florida has rules limiting purchases by people from certain countries. Ask us before you start. To compare prices in your currency, use XE's currency converter.
New construction
Builders often offer incentives such as rate buydowns and closing cost credits. Bring your own agent on your first visit, at no cost to you: the builder's sales team works for the builder, and most builders won't accept an agent added later.
Explore new constructionCommon questions
What credit score do I need to buy a house?
FHA loans can allow scores from 580 with 3.5% down, and many conventional loans start around 620. Higher scores usually get better rates. If your score needs work, a short plan can often make a real difference within months.
Does it cost me anything to use a buyer's agent?
How a buyer's agent is paid is agreed in writing before you tour homes. Often the seller or builder covers it, but not always, so ask us to explain the options up front.
I'm moving to Florida. What should I know?
Budget carefully for home insurance, which is higher than in many states, and ask about flood zones, HOA and CDD fees. Once you own and live in the home, apply for the Florida homestead exemption by March 1 to reduce your property taxes.
Start your home search with us
A quick, no-pressure call to check your numbers and your options.
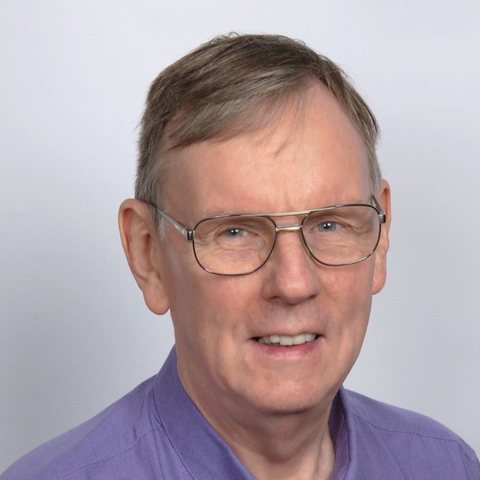
Bill McElhill
- Realtor®, RE/MAX Titanium
- Loan Originator, NEXA Lending · NMLS #2176490
- Call or text 352-988-4900
- WhatsApp Bill
- Mortgages: BillMc@NEXAMortgage.com
- Real estate & general: Bill@HomesCalculator.com
Educational information only. This page gives general information to help you learn and plan. It is not legal, tax, financial or other professional advice, or an offer to lend. For advice on your situation, talk to a licensed professional. Terms of use