Credit
Improve your credit before you buy
A better score can mean a lower rate, a lower payment and more loan options. These steps are free, and you can do them yourself.
Five steps that help most
- Get all three reports free at AnnualCreditReport.com (Equifax, Experian and TransUnion).
- Dispute anything that's wrong, such as accounts that aren't yours, late payments you made on time, or debts listed twice. The FTC has free instructions and a sample dispute letter.
- Pay every bill on time from now on. Payment history is the biggest part of most scores. Set up autopay for at least the minimum.
- Lower your card balances, ideally below 30% of each limit, and lower still if you can. This often raises scores fastest.
- Don't open or close accounts right before or during a home purchase. New credit and closed old cards can both lower your score.
What lenders look at
- Your middle score of the three bureaus (for a couple, lenders usually look at both).
- Recent late payments, especially in the last 12 months.
- Collections, judgments and bankruptcies, and how long ago they happened.
- Your debt-to-income ratio, which depends on your monthly payments, not your score.
Rate shopping is fine: several mortgage credit checks within a short window usually count as one.
Common myths
"Paying off a collection removes it."
It usually stays on your report, but shows as paid. Some newer scoring models ignore paid collections, and paid medical collections are now removed by the bureaus.
"Closing old cards helps."
It can hurt, by shortening your history and raising your utilization. Keep old cards open if they have no annual fee.
"My income affects my score."
It doesn't. Income matters to lenders for your DTI, but it isn't part of your credit score.
"Someone can erase my bad credit for a fee."
Accurate, current information can't legally be removed. Be wary of anyone who promises it.
Credit terms explained Test your credit knowledge
Common questions
What credit score do I need to buy a home?
It depends on the loan. FHA can go as low as 580 with 3.5% down (500 with 10% down), and many conventional loans look for about 620 or higher. Higher scores get better rates, so even a 20 to 40 point gain can lower your payment.
How fast can my score improve?
Paying credit card balances down often shows up within one or two billing cycles. Late payments and collections take longer to fade, but on-time payments from now on start helping right away.
Should I pay a credit repair company?
You can do everything a credit repair company does yourself, for free: get your reports, dispute errors and build good habits. No one can legally remove accurate, current negative information.
Will checking my own credit hurt my score?
No. Checking your own reports is a soft inquiry. Get them free at AnnualCreditReport.com.
General education only. Bill McElhill is not a credit repair organization and does not charge for credit advice. Results vary and no score improvement is guaranteed.
Get a free credit game plan
We can look at what's holding your score back and which steps would help most before you apply, at no cost.
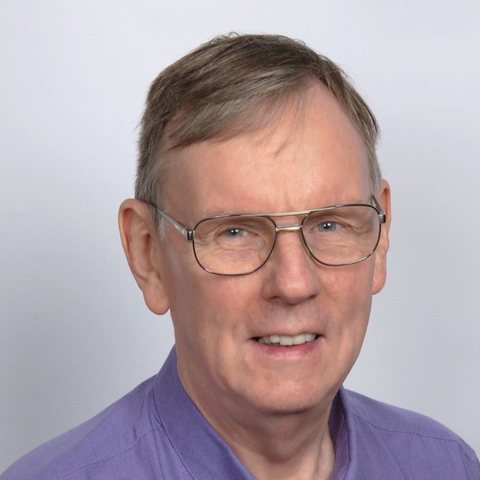
Bill McElhill
- Realtor®, RE/MAX Titanium
- Loan Originator, NEXA Lending · NMLS #2176490
- Call or text 352-988-4900
- WhatsApp Bill
- Mortgages: BillMc@NEXAMortgage.com
- Real estate & general: Bill@HomesCalculator.com
Educational information only. This page gives general information to help you learn and plan. It is not legal, tax, financial or other professional advice, or an offer to lend. For advice on your situation, talk to a licensed professional. Terms of use