Your Home Roadmap
Your Home Roadmap: every step, in order
Pick what you're planning. Each step shows what you do, what we do for you and how long it usually takes. Hover over a step, or tap More detail, for the questions to ask, who's involved and what it costs.
What are you planning?
Roadmap: buying a home
From 'should I buy?' to the keys. Most purchases take 30 to 45 days from accepted offer to closing; the search before that is up to you.
Decide if buying is right for you
A week or twoCan I buy a house? →You
- Think about how long you plan to stay (buying usually pays off after 3 to 5 years)
- Compare the true cost of owning with your rent
We
- Talk it through with you, with no pressure and no obligation
Why it matters: Buying costs money up front (down payment, closing costs, moving) and you build equity over time. If you may move again within a couple of years, renting can work out cheaper.
Questions to ask
- How long will I stay in the area?
- Is my job and income steady?
- Do I have savings left over after the down payment for repairs and emergencies?
- What will I pay each month, including taxes, insurance and HOA fees, not just the loan?
- Who's involved
- You, and us if you'd like a second opinion. No cost.
- What it costs
- Free.
Tip: Try the Rent vs buy calculator with your real rent. It shows the year buying starts to come out ahead.
Know your budget
An eveningHow much can I afford? →You
- Work out a monthly payment you're comfortable with
- Check your credit and savings
We
- Show the true monthly cost, including taxes, insurance, HOA and CDD fees
Why it matters: The most a lender will approve isn't always the most you should spend. Your budget should leave room for savings, repairs and life.
Questions to ask
- What's my credit score, and is anything on my report wrong?
- How much do I have for the down payment and closing costs?
- What monthly payment would still let me save each month?
- Who's involved
- You. A free credit report is available at AnnualCreditReport.com.
- What it costs
- Free.
Tip: In Florida, insurance and HOA or CDD fees can add hundreds a month. Always budget for the full payment.
Get pre-approved
1 to 3 daysStart my pre-approval →You
- Apply online and send pay stubs, W-2s or tax returns, bank statements and ID
We
- Review your credit and income, compare loans from over 300 lenders, and give you a pre-approval letter
Why it matters: A pre-approval tells you exactly what you can borrow and shows sellers you're serious. Many sellers won't look at an offer without one.
Questions to ask
- Which loan types fit me (conventional, FHA, VA, USDA)?
- What would my rate and monthly payment be?
- How much cash will I need at closing?
- How long does the pre-approval last?
- Who's involved
- A licensed loan officer (that's us).
- What it costs
- Free. A credit check is part of it.
Tip: Shopping lenders within about 14 days counts as one credit inquiry in most scoring models.
Check for down payment help
About a weekFind down payment help →You
- Find out which grants and programs you may qualify for
We
- Match the program to the right loan and check its rules and deadlines
Why it matters: Florida has state and county programs that can help with the down payment and closing costs. Some are forgiven over time; others are repaid when you sell.
Questions to ask
- Do I qualify as a first-time buyer? (Often: no ownership in the last 3 years.)
- Is there an income or price limit?
- Does the help have to be repaid, and when?
- Is a homebuyer class required?
- Who's involved
- Your loan officer, and sometimes a housing counselor.
- What it costs
- Usually free. Some programs require a short class, often low cost.
Tip: Funds can run out. Ask early so it doesn't hold up your closing.
Choose your Realtor and see a few homes
1 dayGet matching homes sent to me →You
- Sign a written buyer agreement (needed before touring homes)
- List your must-haves and the areas you'd like to see
We
- Explain how we're paid, then set up an MLS search so new homes reach you first
What Bill does differently: Something Bill does early on: he takes you to see a few homes in your price range, so you see what your budget really buys before you commit to anything.
Why it matters: Your Realtor represents you: finding homes, checking value, writing the contract and negotiating. Since 2024, a written agreement is needed before any home tour, and it states how your agent is paid.
Questions to ask
- How are you paid, and can the seller contribute?
- How will you keep me updated?
- Can the agreement be short or limited to certain homes?
- Who's involved
- A licensed Realtor.
- What it costs
- Set out in your written agreement. Often paid wholly or partly by the seller, but it's negotiable.
Tour homes and choose one
Often 2 to 8 weeksHome viewing checklist →You
- Visit homes, compare neighborhoods, HOA rules and fees
We
- Show homes, pull recent sales, and run the real monthly cost for each one
Why it matters: Seeing several homes helps you know a good one when you find it. Notes and photos help you compare later.
Questions to ask
- How old are the roof, AC and water heater?
- What are the HOA or CDD fees, and what do they cover?
- Is it in a flood zone? What would insurance cost?
- What have similar homes nearby sold for?
- Who's involved
- You and your Realtor.
- What it costs
- Free.
Tip: Visit at different times of day: traffic, noise and light can change a lot.
Make an offer
1 to 3 daysEstimate my cash to close →You
- Agree the price, terms and closing date
- Pay the escrow deposit, usually within 3 days of acceptance
We
- Prepare the contract on the standard Florida forms and negotiate for you
Why it matters: Your offer is more than price: the deposit, inspection period, financing terms, closing date and any seller credit all matter.
Questions to ask
- What have similar homes sold for, and how long were they on the market?
- Should I ask for closing costs instead of a lower price?
- What happens to my deposit if the loan or inspection falls through?
- Who's involved
- You, your Realtor, the seller and their agent. The deposit is held by a title company or broker.
- What it costs
- An escrow deposit, often 1% to 3% of the price. It counts toward your purchase.
Tip: Never wire money based on an email alone. Call the title company on a number you know is real.
Inspections and insurance
Usually 10 to 15 daysWhat an inspector checks →You
- Have the home inspected (and a wind-mitigation and 4-point report)
- Get insurance quotes
We
- Review the reports with you and negotiate repairs or credits
Why it matters: The inspection period is your chance to find problems and walk away or renegotiate. In Florida, insurers often require a 4-point report on older homes, and a wind-mitigation report can lower your premium.
Questions to ask
- What are the biggest repairs, and roughly what would they cost?
- Will the roof and AC pass the insurer's checks?
- Is a termite (WDO) inspection or a survey worth getting?
- Who's involved
- Home inspector, insurance agent, sometimes a surveyor or termite inspector.
- What it costs
- Typical ranges: home inspection $350 to $600, wind-mitigation $75 to $150, 4-point $100 to $200, survey $350 to $600. Prices vary.
Tip: Get insurance quotes in the first few days. In Florida, insurance can change whether a home is affordable.
Appraisal and loan approval
2 to 3 weeksWhat underwriting means →You
- Answer document requests quickly
- Don't change jobs or open new credit
We
- Order the appraisal and steer the loan through underwriting to 'clear to close'
Why it matters: The lender checks the home's value (appraisal) and your paperwork (underwriting). 'Clear to close' means the loan is fully approved.
Questions to ask
- What happens if the appraisal comes in low?
- Is anything still outstanding on my file?
- When will I get my Closing Disclosure?
- Who's involved
- Your loan officer, the appraiser and the underwriter.
- What it costs
- Appraisal often $500 to $800, usually paid up front or at closing.
Tip: Big deposits, new credit cards, a car loan or a job change can delay or stop the loan. Ask us first.
Final check
3 days before closingWhat the Closing Disclosure is →You
- Review your Closing Disclosure
- Do the final walk-through
- Set up utilities in your name from closing day
We
- Check every figure on the Closing Disclosure and coordinate with the title company
Why it matters: By law you get the Closing Disclosure at least 3 business days before closing, so you can check the final numbers.
Questions to ask
- Do these numbers match my Loan Estimate?
- Were the agreed repairs done?
- Exactly how much do I bring, and how do I send it safely?
- Who's involved
- You, your loan officer, your Realtor and the title company.
- What it costs
- No extra cost.
Tip: Confirm wiring instructions by phone with the title company before sending any money.
Closing day: get your keys
About an hourWhat to do after closing →You
- Sign the documents and get your keys
- Apply for the homestead exemption by March 1
We
- Attend closing with you and stay on hand after you move in
Why it matters: You sign the loan and the deed is recorded. Then the home is yours.
Questions to ask
- Where are my copies of everything?
- Who do I pay, and when is my first payment?
- How do I get the garage remotes, codes and mailbox key?
- Who's involved
- Title company or closing attorney, you, and often your Realtor and loan officer.
- What it costs
- Your cash to close, from your Closing Disclosure.
Tip: See the After closing roadmap for your first-month checklist, including homestead.
Times are typical, not guaranteed; every purchase and sale is different.
Roadmap: selling a home
From 'should I sell?' to the money in your account. Once you accept an offer, closing usually follows in 30 to 45 days.
Look before you decide
A day or twoThinking of moving up? →You
- Go and see homes in the area you'd move to
- Ask yourself: do I really want to move?
We
- Show you homes where you're thinking of going, with what they'd cost each month
What Bill does differently: Before talking about listing, Bill takes you to see where you'd be moving to. If it isn't right, you've lost nothing.
Why it matters: Many people list first and only then find out what their next home costs. Seeing it first tells you whether moving is right, before you spend money getting your home ready.
Questions to ask
- What would I get for my money there?
- Would my monthly cost go up or down?
- Would I be happier there, or is it better to improve the home I have?
- Who's involved
- You and your Realtor.
- What it costs
- Free, with no obligation to sell.
Find out what it's worth
1 dayWhat's my home worth? →You
- Get an online estimate, then a personal valuation
We
- Prepare a market analysis from recent nearby sales and your home's condition
Why it matters: Online estimates can miss upgrades and condition. A market analysis uses recent sales of similar homes nearby.
Questions to ask
- Which recent sales are most like my home?
- What would raise or lower the price?
- How long are similar homes taking to sell?
- Who's involved
- Your Realtor. An appraiser only if you want one.
- What it costs
- Free from us. A pre-listing appraisal is optional, often $400 to $700.
Tip: Price is the biggest factor in how fast a home sells.
Know what you'll walk away with
An eveningSeller net proceeds →You
- Check your loan payoff and moving costs
We
- Estimate your net proceeds after the loan payoff, commission, title and closing costs
Why it matters: Knowing your net tells you what you can spend on the next home.
Questions to ask
- What's my exact loan payoff?
- What are the Florida deed stamps on my price?
- Are there HOA estoppel fees or special assessments?
- Who's involved
- You, your Realtor and the title company.
- What it costs
- Typical seller costs: commission (negotiable), Florida deed stamps ($0.70 per $100 of price in most counties), title and closing fees, any agreed buyer credits.
Tip: Ask your lender for a payoff figure. It's usually a little more than the balance on your statement.
Decide the order: buy or sell first?
A conversationThe buying and selling roadmap →You
- Decide whether to buy first, sell first, or make a contingent offer
We
- Show the numbers for each option
Why it matters: If you're buying another home, the order matters. Each way has costs and risks.
Questions to ask
- Could I carry two payments for a while?
- Could I stay in my home after closing (a rent-back)?
- Would a bridge loan or HELOC help?
- Who's involved
- Your Realtor and your loan officer. We're both, so one plan covers both sides.
- What it costs
- Free.
Prepare the home
1 to 4 weeksGetting your home ready →You
- Repair, declutter and clean
- Gather HOA documents, permits and warranties
We
- Suggest the few fixes that pay for themselves, and the ones to skip
Why it matters: First impressions online and at the door decide whether buyers come to see it.
Questions to ask
- Which repairs would a buyer's inspector flag?
- Should I paint, stage or leave it?
- Do I have permits for past work?
- Who's involved
- You, plus handymen, cleaners, painters or a stager if needed.
- What it costs
- From almost nothing to a few thousand dollars. We'll suggest only what's likely to pay off.
Tip: A pre-listing inspection can avoid surprises later.
Price and list
1 weekYou
- Sign the listing agreement and complete the seller's disclosure
We
- Price it from the data, arrange photos, list it on the MLS and market it
Why it matters: The first two weeks on the market bring the most interest, so the right price from day one matters.
Questions to ask
- How will you market my home?
- How will showings be arranged?
- What's the commission, and is it negotiable?
- Who's involved
- You, your Realtor and a photographer.
- What it costs
- Commission is set out in your listing agreement and is negotiable. Photos are usually included.
Tip: In Florida you must tell buyers about known defects that affect the home's value.
Showings and open houses
Often 1 to 6 weeksBuyer Payment Sheet for your listing →You
- Keep the home show-ready
We
- Schedule showings, collect feedback and adjust if needed
Why it matters: Feedback from showings tells us whether the price and presentation are right.
Questions to ask
- What are buyers saying?
- Should we adjust anything after two weeks?
- Who's involved
- You and your Realtor.
- What it costs
- No extra cost.
Tip: Secure valuables and medications during showings.
Review offers and negotiate
1 to 3 daysYou
- Choose the offer that fits you best, not just the highest price
We
- Compare price, financing, contingencies and dates, and negotiate for you
Why it matters: Strong financing and fewer conditions can be worth more than a slightly higher price.
Questions to ask
- Is the buyer pre-approved, and with what loan?
- What's the deposit and inspection period?
- Does the closing date work with my move?
- Who's involved
- You, your Realtor and the buyer's agent.
- What it costs
- No extra cost.
Inspection and appraisal
2 to 3 weeksYou
- Respond to repair requests
We
- Negotiate repairs or credits and keep the buyer's loan on schedule
Why it matters: The buyer can ask for repairs or walk away during the inspection period. The appraisal must support the price for most loans.
Questions to ask
- Should I repair, give a credit or lower the price?
- What if the appraisal is low?
- Who's involved
- The buyer's inspector and appraiser; you and your Realtor respond.
- What it costs
- Any repairs or credits you agree to.
Get ready to close
The last weekYou
- Plan your move
- Keep insurance and utilities on until closing, then transfer them
We
- Coordinate the title company, your loan payoff and any HOA paperwork
Why it matters: The title company pays off your loan and clears the title so the sale can close.
Questions to ask
- Where do I sign, and do I need to be there?
- How will my proceeds be paid?
- Who's involved
- Title company, your Realtor and your lender.
- What it costs
- Covered in your closing figures.
Tip: Leave keys, remotes, codes and manuals for the buyer.
Closing day
About an hourYou
- Sign and hand over the keys
We
- Make sure your proceeds are sent to you
Why it matters: Once the deed is recorded, the sale is complete and your money is sent.
Questions to ask
- When will my proceeds arrive?
- When should I cancel my homeowner's insurance?
- Who's involved
- Title company or closing attorney.
- What it costs
- Deducted from your proceeds.
Tip: Your old lender should refund any escrow balance within 30 days.
Times are typical, not guaranteed; every purchase and sale is different.
Roadmap: buying and selling at the same time
Selling one home and buying the next means two timelines that have to meet. Here's how they fit together.
What Bill does differently: before you list, he takes you to see homes where you'd be moving to, so you can decide whether moving is really right before spending anything.
Selling
- Find your home's value and your likely net proceeds
Buying
- Get pre-approved, including whether you could carry both payments for a while
- 2
Choose your order
- 3
List and search
Selling
- Prepare, price and list your home
Buying
- Search with your new budget and lined-up loan
- 4
Two contracts, one timeline
Selling
- Accept an offer with a closing date that works
Buying
- Make an offer with a closing date that matches
- 5
Back-to-back closings
Selling
- Close the sale, often in the morning
Buying
- Close the purchase the same day or soon after, using your sale proceeds
As your Realtor and loan officer, we time both sides together so the dates line up. Times vary; nothing here is guaranteed.
Roadmap: moving to a new area
Moving to a different town, or to Florida from elsewhere? Here's the order that saves the most stress.
Decide why and when
A week or twoCan I buy a house? →You
- Write down why you're moving and your must-haves
- Pick a target date (a job start, a lease end, the school year)
We
- Help you work out what you can afford in the new area
Why it matters: Clear reasons and a date make every later decision easier.
Questions to ask
- Is my income changing with the move?
- Do I need to sell, end a lease or both?
- Who's involved
- You.
- What it costs
- Free.
Research the area
2 to 4 weeksFlorida homeowner costs →You
- Visit at different times of day
- Check commute times, flood zones, insurance, taxes and HOA or CDD fees
We
- Give you the facts: recent prices, typical costs and flood-zone maps
Why it matters: The same price can mean very different monthly costs from one area to the next, mostly because of insurance, flood zones, HOA and CDD fees.
Questions to ask
- What would insurance cost here?
- Is there a CDD fee on the tax bill?
- How long is the drive to work at rush hour?
- Who's involved
- You, with our facts and figures.
- What it costs
- Travel for a visit.
Tip: We give facts, not opinions about who lives where. The choice of neighborhood is always yours.
Budget for the move
An eveningSavings planner →You
- Add up movers, travel, deposits and any time paying for two homes
We
- Show the costs of each option side by side
Why it matters: Moves cost more than most people expect, especially over long distances.
Questions to ask
- Will my employer help with moving costs?
- How long might I pay for two homes?
- Who's involved
- You.
- What it costs
- Long-distance moves can run into thousands. Get 3 written quotes.
Choose: buy now, rent first, or sell first
A conversationRent vs buy →You
- Decide whether to buy before you move or rent while you learn the area
We
- Compare the costs of each with your real numbers
Why it matters: Renting first lets you learn the area before buying. Buying first avoids moving twice.
Questions to ask
- How sure am I about the area?
- Would a short lease be easy to find?
- Who's involved
- You, your Realtor and your loan officer.
- What it costs
- Free.
Get pre-approved and plan your sale
1 to 3 daysStart my pre-approval →You
- Apply for a pre-approval
- If you own a home, get its value and your net proceeds
We
- Pre-approve you and, if you're selling, plan both sides together
Why it matters: A pre-approval lets you act fast, even from a distance.
Questions to ask
- Can I use my sale proceeds for the down payment?
- Can I qualify before I start my new job?
- Who's involved
- Your loan officer, and your Realtor if you're selling.
- What it costs
- Free.
Tip: Moving from outside our area? We can introduce you to a trusted agent where you live now.
Find your home from a distance
Often 2 to 8 weeksGet matching homes sent to me →You
- Get matching homes sent to you
- Tour by video call, then visit the best ones
We
- Tour homes for you on live video and tell you what photos don't show
Why it matters: Video tours narrow the list so your trip is spent on the homes that matter.
Questions to ask
- What's next door and across the street?
- Any noise, smells or traffic?
- Who's involved
- You and your Realtor.
- What it costs
- Free.
Plan the move
4 to 8 weeks beforeHome viewing checklist →You
- Book movers, set utilities at both ends, forward mail
- Arrange school records, medical records and pets
We
- Coordinate closing dates with your move
Why it matters: Booking early gets better prices and dates.
Questions to ask
- Are the movers licensed and insured?
- What's the delivery window?
- Who's involved
- Movers, utility companies, schools and doctors.
- What it costs
- Varies. Get written quotes.
Arrive and settle in
First 30 daysWhat to do after closing →You
- New to Florida? Get a Florida driver license and registration (short deadlines: check FLHSMV)
- Register to vote and apply for homestead by March 1
We
- Help with anything you need locally
Why it matters: Florida gives new residents short deadlines for licenses and vehicle registration.
Questions to ask
- Which documents do I need at the DMV office?
- Who's involved
- FLHSMV (tax collector offices), county property appraiser.
- What it costs
- State fees apply.
Times are typical, not guaranteed; every purchase and sale is different.
Roadmap: refinancing your mortgage
Replacing your mortgage with a new one. Most refinances take 3 to 6 weeks from application to closing.
Decide your goal
An eveningRefinance calculator →You
- Lower payment, shorter term, cash out, remove mortgage insurance, or switch from an adjustable rate
We
- Talk through which goal saves you the most
Why it matters: The right refinance depends on what you want. A lower rate isn't always the biggest saving.
Questions to ask
- How long will I stay in the home?
- Would extra payments do the same job without refinancing?
- Who's involved
- You and your loan officer.
- What it costs
- Free.
Check the numbers
An eveningRefinance calculator →You
- Compare your new payment and total cost with your current loan
We
- Work out your break-even point: costs divided by monthly savings
Why it matters: If you'll move before the break-even point, the refinance may cost more than it saves.
Questions to ask
- What are the total closing costs?
- Am I restarting a 30-year loan?
- How much total interest will I pay either way?
- Who's involved
- Your loan officer.
- What it costs
- Free.
Tip: Rate alerts can tell you when rates reach the level that makes sense for you.
Check your credit and equity
1 dayWhat's my home worth? →You
- Check your credit report
- Estimate your home's value
We
- Show how your score and equity affect your rate
Why it matters: More equity and a higher credit score usually mean a better rate, and 20% equity can remove mortgage insurance.
Questions to ask
- Is anything on my credit report wrong?
- Who's involved
- You and your loan officer.
- What it costs
- Free.
Apply and compare
1 to 3 daysStart my application →You
- Apply and send your documents
We
- Shop over 300 lenders and give you a Loan Estimate
Why it matters: The Loan Estimate is a standard form that makes offers easy to compare.
Questions to ask
- What's the APR, not just the rate?
- Are there points, and are they worth it?
- Who's involved
- Your loan officer.
- What it costs
- Free to apply. Some lenders charge a small fee up front, often for the appraisal.
Lock your rate
Same dayYou
- Decide when to lock
We
- Lock your rate and tell you when the lock expires
Why it matters: A rate lock protects you if rates rise before closing.
Questions to ask
- How long is the lock?
- What happens if closing is delayed?
- Who's involved
- Your loan officer.
- What it costs
- Usually free for standard periods.
Appraisal and underwriting
2 to 4 weeksWhat underwriting means →You
- Answer document requests quickly
We
- Order the appraisal (sometimes waived) and steer the loan to 'clear to close'
Why it matters: The lender checks the home's value and your paperwork.
Questions to ask
- Could the appraisal be waived?
- What if the value comes in low?
- Who's involved
- Appraiser and underwriter.
- What it costs
- Appraisal often $500 to $800 if needed.
Closing
About an hourWhat the Closing Disclosure is →You
- Review the Closing Disclosure, then sign
We
- Check every figure and attend with you
Why it matters: For a refinance of the home you live in, you usually have 3 business days after signing to change your mind before the loan funds.
Questions to ask
- Do the final numbers match my Loan Estimate?
- Who's involved
- Title company or closing attorney.
- What it costs
- Typically 2% to 5% of the loan, including Florida mortgage taxes. Some costs can be rolled into the loan.
After closing
First 30 to 60 daysMortgage payoff plan →You
- Keep paying your old loan until it's confirmed paid off
- Watch for your escrow refund and your new first payment date
We
- Make sure the old loan is paid off and stay on hand for questions
Why it matters: Your old lender must refund any escrow balance, usually within 30 days of payoff.
Questions to ask
- When is my first new payment due?
- Who services the new loan?
- Who's involved
- Your old and new lenders.
- What it costs
- No extra cost.
Tip: You often don't make a payment the month after closing. It isn't free: that interest was in your closing figures.
Times are typical, not guaranteed; every purchase and sale is different.
Roadmap: renting a home
Finding and keeping a rental, and getting ready to buy one day if you'd like to.
Set your rent budget
An eveningRent vs buy →You
- Work out the rent you can afford, plus deposits, moving and renter's insurance
We
- Show you how rent compares with owning, if you're curious
Why it matters: Many landlords look for income of about 3 times the rent. You'll often need first month's rent and a deposit up front.
Questions to ask
- What can I afford and still save each month?
- Who's involved
- You.
- What it costs
- Free.
Know what you need
An eveningHome wish list →You
- List the area, size, pets, parking and lease length you want
We
- Answer any questions
Why it matters: A clear list makes it faster to say yes when the right place comes up.
Questions to ask
- Are pets allowed, and is there a pet fee?
- Who pays which utilities?
- Who's involved
- You.
- What it costs
- Free.
Search and tour
1 to 4 weeksYou
- Tour in person or by live video before paying anything
We
- Point you to safe ways to search
Why it matters: Rental scams are common: fake listings ask for deposits on homes that aren't for rent.
Questions to ask
- Is the person showing it the owner or a licensed manager? (Check the county property appraiser's site.)
- Who's involved
- Landlord or property manager, sometimes a Realtor.
- What it costs
- Free.
Tip: Never wire money or pay with gift cards for a home you haven't seen.
Apply
1 to 3 daysYou
- Send ID, proof of income and references
- Pay the application fee
We
- Answer questions about the process
Why it matters: Landlords usually check credit, background and rental history.
Questions to ask
- What's the fee, and is it refundable?
- What are the approval rules?
- Who's involved
- Landlord or property manager. Some HOAs must also approve tenants.
- What it costs
- Application fees vary, often $50 to $100 per adult.
Tip: Fair housing law protects you from discrimination.
Read and sign the lease
1 dayYou
- Read every page before you sign
We
- Explain common terms if you ask
Why it matters: The lease sets the rent, length, renewal, repairs, pets and the cost of leaving early.
Questions to ask
- What happens if I need to leave early?
- Who handles repairs, and how fast?
- Can rent go up at renewal?
- Who's involved
- You and the landlord.
- What it costs
- First month's rent and deposit, often due at signing.
Move in
Moving dayYou
- Do a move-in inspection with dated photos
- Get renter's insurance and set up utilities
We
- Help if you have questions
Why it matters: Photos of the condition on day one protect your deposit when you leave.
Questions to ask
- Where are the water shutoff and breaker box?
- Who's involved
- You and the landlord.
- What it costs
- Renter's insurance is often $10 to $25 a month.
Living there
During the leaseSavings planner →You
- Pay on time and keep records
- Ask for repairs in writing
We
- Keep in touch if you'd like help planning to buy
Why it matters: On-time rent builds a history that helps when you apply to buy.
Questions to ask
- How much notice will the landlord give before entering?
- Who's involved
- You and the landlord.
- What it costs
- Your rent.
Moving out or buying
1 to 2 months beforeCan I buy a house? →You
- Give written notice as your lease requires
- Clean and photograph the home
We
- If you're ready, show you what buying would cost and get you pre-approved
Why it matters: In Florida, a landlord must return your deposit within 15 days, or send written notice of a claim within 30 days.
Questions to ask
- Where should my deposit be sent?
- Who's involved
- You and the landlord.
- What it costs
- Moving costs.
Tip: Thinking of buying? Down payment help may mean you need less saved than you think.
Times are typical, not guaranteed; every purchase and sale is different.
Roadmap: after closing: your first year
You've got the keys. Here's what to do next, from the first day to your first anniversary.
Before closing: set up utilities
The week beforeYou
- Put electric, water and sewer, trash and internet in your name from closing day
We
- Give you a utilities checklist before closing
Why it matters: Some providers need a few days' notice, and some ask for a deposit.
Questions to ask
- Is a deposit needed, or can it be waived with good credit?
- Is trash collected by the city, the county or the HOA?
- Who's involved
- Utility companies.
- What it costs
- Some charge a deposit or connection fee.
Closing day
Day 1You
- Rekey the locks, change garage and alarm codes
- Keep your closing documents somewhere safe
We
- Attend closing and answer questions afterwards
Why it matters: You don't know who still has keys. Your Closing Disclosure is needed for taxes and any future refinance.
Questions to ask
- Where will my recorded deed and title policy be sent?
- Who's involved
- You, and a locksmith if needed.
- What it costs
- Rekeying is often around $100 to $200.
First week
Days 1 to 7You
- Change your address (USPS, banks, employer, IRS)
- Find the main water shutoff and breaker box
- Test smoke alarms, change the AC filter
We
- Check in to see how you're settling
Why it matters: Small checks early prevent big problems later.
Questions to ask
- When was the AC last serviced?
- Who's involved
- You.
- What it costs
- Small.
First mortgage payment
About 30 to 60 daysYou
- Make your first payment on time
- Watch for a letter if your loan moves to a new servicer
We
- Help if anything looks wrong
Why it matters: Loans are often transferred to a new company that collects the payments. You'll get letters from both companies, and your terms don't change.
Questions to ask
- Is this transfer letter genuine? (Call the number on your old statement.)
- Who's involved
- Your loan servicer.
- What it costs
- Your payment.
Tip: Scammers send fake transfer letters. Check before you change where you pay.
Homestead exemption
By March 1Florida homeowner costs →You
- Apply with your county property appraiser
We
- Send you the link and answer your questions
Why it matters: If it's your main home on January 1, Florida's homestead exemption can take up to $50,000 off its taxable value, and the Save Our Homes cap limits yearly increases.
Questions to ask
- Can I bring my Save Our Homes benefit from my last Florida home? (Portability: apply within 3 years.)
- Who's involved
- County property appraiser.
- What it costs
- Free to apply.
Tip: Missing March 1 can cost you a year of savings.
Hurricane season
June 1 to November 30Florida insurance →You
- Plan shutters or panels, supplies and an evacuation route
- Store documents and photos of your belongings online
We
- Share checklists before the season
Why it matters: Being ready protects your family and helps any insurance claim.
Questions to ask
- What's my hurricane deductible?
- Do I need flood insurance?
- Who's involved
- You and your insurance agent.
- What it costs
- Varies.
Tip: Flood insurance through the NFIP usually has a 30-day waiting period, so don't wait for a storm.
Property taxes and insurance renewal
November, then yearlyYou
- Check your tax bill (paying in November gets a 4% discount if you pay it yourself)
- Shop your insurance before it renews
We
- Review your costs with you
Why it matters: If you have an escrow account, your lender pays these and may adjust your payment each year.
Questions to ask
- Why did my payment change after the escrow review?
- Who's involved
- Tax collector, insurance agent, loan servicer.
- What it costs
- Your tax and insurance.
Your first anniversary
After a yearMortgage payoff plan →You
- Look at your equity, rate and goals
We
- A free yearly review: your value, your rate, whether mortgage insurance can come off, and whether refinancing makes sense
Why it matters: Small changes, like extra payments or dropping mortgage insurance, can save thousands.
Questions to ask
- Can I remove mortgage insurance yet? (Often at 20% equity.)
- Who's involved
- You and us.
- What it costs
- Free.
Tip: Budget about 1% to 2% of the home's value each year for maintenance.
Times are typical, not guaranteed; every purchase and sale is different.
Common questions
How long does it take to buy a house?
Getting pre-approved takes a few days and the search is up to you. Once your offer is accepted, closing usually takes 30 to 45 days with a mortgage, or as little as one to two weeks with cash.
How long does it take to sell a house?
Preparing and listing usually takes a few weeks, and time on the market depends on price, condition and the local market. After you accept an offer, closing usually follows in 30 to 45 days.
Should I buy or sell first?
It depends on your equity, your budget and how much risk you're comfortable with. Buying first is easier on the move but may mean two payments for a while; selling first gives you certainty about your budget but may need a rent-back or short-term rental. The Buy before you sell planner compares your options.
How long does a refinance take?
Usually 3 to 6 weeks from application to closing, sometimes faster if the appraisal is waived.
When do I apply for the Florida homestead exemption?
Apply with your county property appraiser by March 1 if the home was your main home on January 1.
Start your plan with us
Tell us where you are on your roadmap and we'll map out your next steps, with real numbers for your situation.
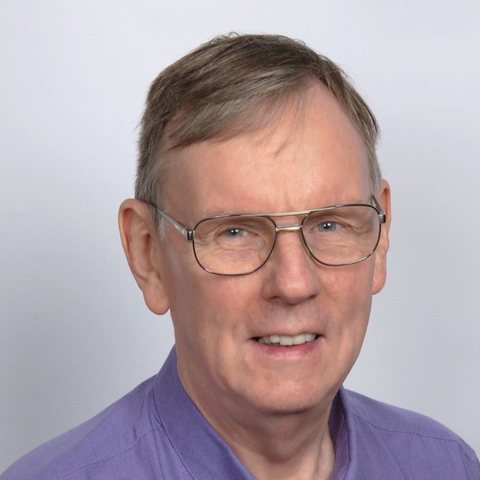
Bill McElhill
- Realtor®, RE/MAX Titanium
- Loan Originator, NEXA Lending · NMLS #2176490
- Call or text 352-988-4900
- WhatsApp Bill
- Mortgages: BillMc@NEXAMortgage.com
- Real estate & general: Bill@HomesCalculator.com
Educational information only. This page gives general information to help you learn and plan. It is not legal, tax, financial or other professional advice, or an offer to lend. For advice on your situation, talk to a licensed professional. Terms of use